Table of contents
An insufficiently documented transfer pricing study can lead to observations and adjustments during a tax audit. For an accounting firm, promptly identifying related-party transactions helps assess compliance risks and organize evidence before filing tax returns.
This guide to transfer pricing in Mexico is aimed at accounting firms, tax advisors, and companies that need to understand their obligations to the SAT, the applicable methods, and when an independent valuation may be useful.
What are transfer prices?
Transfer pricing refers to the terms—price, margin, or consideration—agreed upon between related parties: two companies within the same group, a parent company and its subsidiary, or two companies controlled by the same individuals. These transactions may involve the transfer of tangible assets, intangible assets (trademarks, technology, know-how), services, financing, or leases.
For example, when a Mexican company sells machinery to another company within the same corporate group, the agreed-upon amount constitutes a transfer price. For tax purposes, this transaction must be analyzed according to the arm's length principle, That is, considering the conditions that independent parties would agree upon in comparable circumstances.
Examples of transfer pricing in Mexico
- Sale of machinery between companies within the same group. A Mexican company transfers industrial machinery to a subsidiary. It must be analyzed whether the agreed-upon consideration is based on arm's length conditions.
- Intragroup administrative services. A parent company provides accounting, technology, or administrative services to its subsidiaries. The service provided, its usefulness to the recipient, and the consideration are evaluated.
- Use of trademarks and technology. An entity allows a related company to use a trademark, patent, or technology in exchange for royalties. The analysis considers relevant functions, assets, risks, and comparables.
- Related party loans. One company lends funds to another entity within the same group. The financial terms, including the interest rate, are analyzed according to the characteristics of the transaction.
In certain transactions, particularly transfers of specialized or intangible assets, an independent valuation can provide supplementary technical evidence. It does not replace a transfer pricing study and is not generally required.
The principle that governs all matter, tas stated in the OECD Guidelines as in Mexican law, it is the arm's length principle , As established in Article 9 of the OECD Model Tax Convention, these transactions must be agreed upon as if the parties were independent of each other. The underlying objective, both for the SAT (Mexican Tax Administration Service) and for the rest of the world's tax authorities, is to prevent profits from being artificially shifted to the jurisdiction with the lowest tax burden.
The obligation is not limited to multinational corporations: relevant transactions may also exist between related parties residing in Mexico. However, the specific duties depend on the type of taxpayer, the transaction, and the exceptions provided by law; it should not be assumed that all companies submit the same studies and declarations.
Legal framework for transfer pricing in Mexico
- Article 76 of the LISR: regulates the obligations of legal entities in operations with related parties and supporting documentation, with conditions and exceptions that must be analyzed for each taxpayer.
- Article 76-A of the Mexican Income Tax Law (LISR) provides for different informational returns—Master File, Local File, and Country-by-Country Return—for taxpayers who meet the legal requirements. The obligation to provide general documentation does not automatically imply filing all three.
- Article 179: defines what is considered a related party and establishes the obligation to apply the arm's length principle.
- Article 180: lists the six accepted valuation methods and the order of precedence for choosing them.
- Article 182: regulates the maquiladora regime and the “safe harbor” mechanism — a simplified option to determine taxable profit, calculated on the value of the assets used in the operation or on costs and expenses, without the need for a complete study of comparables.
Mexico does not create its own framework: it is aligned with the OECD Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations, the international technical reference. When the SAT (Mexican Tax Administration Service) conducts an audit, it generally uses both frameworks.
Who is required to file and what documentation does the SAT require?
| Document | What information does it contain? | When is it appropriate? |
|---|---|---|
| Transfer pricing supporting documentation | Functional, economic and comparability analysis that supports transactions between related parties. | According to the tax regime, the operations carried out and the exceptions provided for in the legislation. |
| Annex 9 of the Multiple Information Declaration (DIM) | Information on transactions with related parties that are reportable to the SAT. | When the taxpayer falls within the presentation requirements applicable to their tax year. |
| Local Information Statement (Local File) | Taxpayer information, related party transactions, and the corresponding analysis. | For those obligated under Article 76-A, Section II, of the LISR. |
| Master File | Structure and activities of the multinational group, intangibles and financing policies. | For those obligated under Article 76-A, Section I, of the LISR. |
| Country-by-Country (CbC) Reporting | Distribution of income, profits, taxes and activities by jurisdiction of the multinational group. | When the specific requirements of article 76-A, section III, of the LISR are met. |
Transfer pricing obligations schedule: 2026
| Reference date | Tax obligation |
|---|---|
| May 15, 2026 | Tax opinion corresponding to the 2025 fiscal year, when applicable. |
| May 15, 2026 | Annex 9 of the Multiple Informative Declaration (DIM), corresponding to the 2025 fiscal year. |
| December 31, 2026 | Local, Master and Country-by-Country information returns for the year 2025, for obligated taxpayers. |
How is a transfer pricing study prepared?
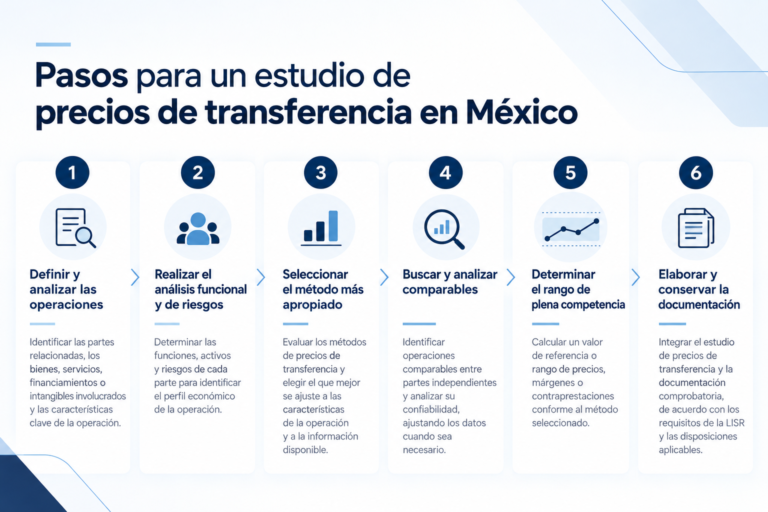
The analysis process is typically organized into six stages that must be adapted to the operation and the required documentation. This sequence is a guideline and does not constitute six independent formal requirements literally established by law.
- Identify related party transactions. List every transaction during the fiscal year between the taxpayer and its related parties: purchase and sale of goods, services, royalties, financing, guarantees, and transfer of personnel. Not just "large" transactions—smaller ones also count for analysis.
- Functional and comparability analysis. Document the functions, assets, and risks of each party. If a transaction requires substantiating the value of tangible or intangible assets, or a business, an independent valuation may be useful; however, it is not mandatory in all cases.
- Selection of the valuation method. Based on the functional analysis and the availability of comparables, one of the six methods of Art. 180 LISR is chosen, respecting the order of precedence explained below.
- Data collection and comparisons. Financial statements, contracts, pricing policies, and independent comparable databases from the correct sector and geography are gathered.
- Determination of arm's length results and adjustments, if applicable. Depending on the method and available comparables, the analysis may produce a value or a range. Where appropriate, statistical procedures are applied and legally required adjustments are assessed.
- Documentation and support. The formal Transfer Pricing Study is prepared, reconciled with Annex 9 of the DIM —and, if applicable, with the Local, Master and Country-by-Country Informative Declarations— and all evidence is kept for a possible review by the SAT.
The six transfer pricing methods
- Comparable Uncontrolled Price (CUP)This method directly compares the agreed-upon price with that of an identical transaction between independent parties. It is the most direct method, but requires nearly identical comparables.
- Resale PricePart of the resale price is sold to an independent third party, and a gross margin comparable to the market rate is deducted. Useful for distributors.
- Additional Cost: part of the production cost and adds a comparable gross profit margin. Common in contract manufacturing.
- Utilities PartitionThis method divides the overall profit among the parts according to their relative contribution (assets, functions, risks). It is used when operations are highly integrated.
- Utilities Partition Residual: variant — first a minimum profit is assigned for basic functions, and the residual is distributed according to the contribution of intangibles or other unique factors.
- Transactional Operating Profit Margins (TNMM/MTU)This compares the operating profit margin against that of comparable companies. In Mexican practice, it is the most widely used because it better tolerates product differences.
| Method | What does it consist of? |
|---|---|
| 1. Comparable Uncontrolled Price (PCNC/CUP) | Compare the price of a transaction between related parties with that of comparable transactions between independent parties. |
| 2. Resale Price | It takes into account part of the resale price to an independent third party and considers a comparable gross margin. It is used, among other cases, in distribution activities. |
| 3. Additional Cost | Analyze the costs of an operation and add a comparable gross profit margin. It can be applied to certain manufacturing or service operations. |
| 4. Utilities Partition | Distribute the profit corresponding to related operations considering the functions, assets and risks of the parties involved. |
| 5. Utilities Partition Residual | First, it assigns returns associated with identifiable contributions and then distributes the residual profit according to the relevant economic contributions of each party. |
| 6. Transactional Operating Profit Margins (MTU/TNMM) | Compare operating profitability indicators with those obtained in comparable independent operations or companies. |
What is the full capacity range?
The arm's length range is a set of prices, considerations, or margins obtained from comparable transactions between independent parties.
Depending on the method used and the information available, the analysis can determine a reference value or a range of results. When several comparables exist, statistical procedures can be applied in accordance with the relevant regulations.
Not all methods necessarily generate an interquartile range.
Illustrative numerical example (MTU/TNMM)
A company has operating costs of MXN 50,000,000 and reports operating profit of MXN 1,200,000 (2.4% of costs). For illustrative purposes only, assume that reliable comparables yield margins ranging from 4% to 7%, with a median margin of 5.5%. The profit at 5.5% would be MXN 2,750,000: this is the target profit, NOT the additional adjustment. The difference from MXN 1,200,000 is MXN 1,550,000. The origin, direction, and amount of any actual tax adjustment require legal and technical analysis of the operations and comparables.
| Concept | Value |
|---|---|
| Operating costs | $50,000,000 MXN |
| Reported operating profit | $1,200,000 MXN |
| Reported margin on costs | 2,4 % |
| Comparable margin range | 4 %–7 % |
| Reference median | 5,5 % |
| Median calculated utility | $2,750,000 MXN |
| Illustrative difference | $1,550,000 MXN |
In this example, the reported operating profit is below the reference range. Applying a median of 5.5% to operating costs results in a profit of MXN 2,750,000.
The difference with respect to the reported profit is $1,550,000 MXN. This difference is for illustrative purposes only and does not automatically constitute a required tax adjustment.Any actual adjustment requires analyzing the operation, the selected method, the comparables, and the applicable legal provisions.
When can you provide an independent appraisal?
The transfer pricing study is based on the analysis of comparable functions, assets, risks, and transactions. In certain cases, an independent valuation may provide additional technical evidence regarding machinery, real estate, businesses, or intangible assets. Its necessity depends on the transaction and should not be assumed to be mandatory in all studies.
Two situations in which it is advisable to consider the support of specialists:
- Maquiladora Safe Harbor (Article 182 of the Mexican Income Tax Law): Taxable income is determined by considering the higher of the legally established results: 6.9% of the total taxable income (TPI) on an asset base determined according to specific tax rules, and 6.5% of the corresponding costs and expenses. The tax base is NOT automatically replaced by the market value obtained in an appraisal. An appraiser may assist in specific situations involving asset analysis or transfers, but this does not imply that an appraisal is a universal requirement for the safe harbor.
- Restructurings and transfers of assets or intangibles: transactions between related parties that include the transfer of machinery, trademarks, technology, or business units may require supporting economic values and market conditions. Depending on the case and the method chosen, an independent valuation may complement the transfer pricing analysis.
For the firm, tax studies and independent valuations can be complementary tools when the transaction involves assets with complex valuations. They should not be presented as mandatory joint services nor as substitutes for the documentation and methods required by the Mexican Income Tax Law (LISR).
Common mistakes in transfer pricing
- Treat Annex 9 of the DIM as an administrative procedure, instead of a data source that the SAT automatically cross-references with other declarations.
- Using outdated comparables or from a different sector just because they are available in an already paid database.
- Not documenting the functional analysis (what functions each part performs, what assets it uses, what risks it assumes).
- Confusing the book value, market value, and tax base of assets, especially when there is a specific legal methodology, such as that provided for the safe harbor of maquiladoras.
- Apply the same method year after year without checking if it is still the most appropriate when business conditions change.
- Ignore “minor” transactions such as intercompany guarantees, related-party loans, or staff transfers.
Transfer pricing checklist for accounting firms
- Does the group have related entities inside or outside of Mexico, and what are the consolidated revenues of the entire group (not just the Mexican entity)?
- What types of intercompany transactions exist? (purchase and sale of goods, services, royalties, financing, guarantees, transfer of personnel)
- Is there a current Transfer Pricing Study for the current fiscal year, or is one from previous years being used without updating?
- If it is a maquiladora: Were the tax rules of Article 182 correctly applied to the asset and cost and expense basis? Are there any asset transfer transactions that require separate valuation evidence?
- Did the exercise involve any restructuring, merger, spin-off, or transfer of intangibles between related parties that requires supporting documentation for their value?
- Was the obligation to submit Annex 9 of the DIM correctly identified, and, where applicable, the Local, Master and Country-by-Country declarations according to their differentiated assumptions?
- Do the comparables used in the study correspond to the correct sector and geography, and are they of a reasonable age?
Frequent questions
Which companies are required to document transfer prices in Mexico?
Companies that conduct transactions with related parties must review the applicable provisions of the Income Tax Law (LISR), their tax regime, and any corresponding exceptions. The obligation to retain documentation does not automatically imply filing the three informational returns required by Article 76-A.
How often should a transfer pricing study be updated?
The study must reflect the operations and market conditions of the corresponding fiscal year. Using a previous study without reviewing comparables or changes in the business may result in findings during a tax audit.
Is a commercial appraisal mandatory to calculate the safe harbor for maquiladoras?
Not generally. Article 182 of the Mexican Income Tax Law (LISR) establishes specific tax rules for determining the asset base and applicable costs and expenses. An independent appraisal may be useful for certain transactions, but it does not automatically replace the tax methodology established by law.
What happens if the SAT determines that a transaction does not comply with the arm's length principle?
Depending on the specific circumstances and applicable regulations, adjustments may be made to the taxpayer's income or deductions, with tax consequences. Penalties or restrictions on deductibility require analysis of the specific situation and are not automatically applied in the event of any discrepancy.
Can the six transfer pricing methods be freely chosen?
Not without justification. Article 180 of the Mexican Income Tax Law (LISR) establishes priority for examining the comparable uncontrolled price method. Other methods may be used when the comparable uncontrolled price method is not appropriate, considering the characteristics of the transaction and the comparable information available.
Do you need to substantiate the value of assets in a related-party transaction?
At ANEPSA Mexico we can evaluate the valuation requirements of machinery, equipment, companies and intangibles to determine the appropriate technical scope for your operation.
Request scope assessment ↘


